How a $4,200 ATM Heist Ended in 72 Hours of Capture
A Tampa Bay man turned $480 in cloned debit cards into $4,200 cash—and a 5-year federal prison sentence. His mistake? He underestimated the power of ATM cameras and the digital trail left by every transaction.
- Posted:
- Last updated: October 8, 2026
- By: Logan Pierce
- 11 minutes
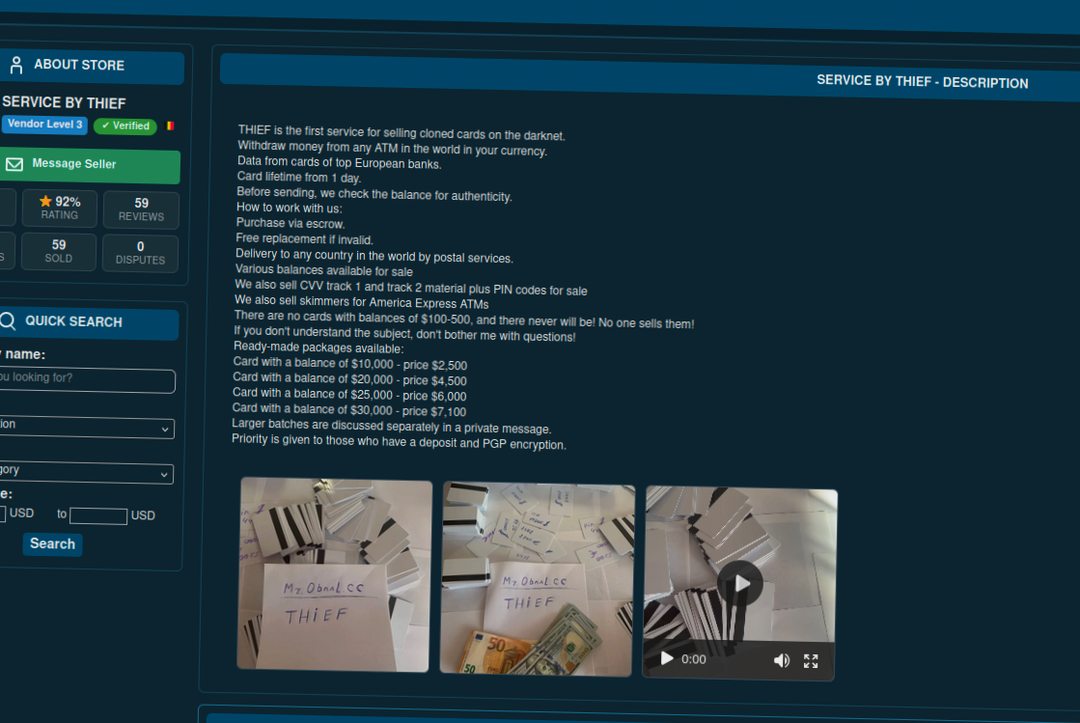
Mark T., a 34-year-old from Tampa Bay, Florida, believed he'd discovered a shortcut to easy money. In November 2024, he spent $480 in cryptocurrency to purchase six cloned debit cards with PIN codes from a darknet marketplace. Each card carried stolen magnetic stripe data from real bank accounts—a standard product you'll find on carding forums dark web.
The first three ATM visits yielded $4,200. The fourth ATM became his last stop as a free man. This isn't a guide on acquiring cloned cards reddit style. It's a breakdown of how a seemingly invisible criminal became highly visible in just 72 hours, why ATM cameras outperform detectives, and how a chain of evidence—from crypto wallets to the U.S. Secret Service—ended in five years behind bars.
The website where the purchase was made offered what looked like a clean transaction: anonymous payment, discreet shipping, and cards that worked on the first try. But Mark didn't account for one critical detail: every ATM is a surveillance device disguised as a cash dispenser.
Key takeaways
- ATM cameras record faces at 1080p resolution with infrared capability—every withdrawal creates prosecutable video evidence.
- Cryptocurrency anonymity breaks at KYC exchanges; Mark's Monero purchase was traced through the centralized exchange where he verified his identity.
- Anti-fraud systems detected the pattern within three days by analyzing geographic clustering and time windows across multiple states.
- Physical evidence (cards, MSR device, matching cash) combined with digital traces (Tor history, transaction logs) created an unbreakable prosecution case.
- The final chain link—the person cashing out—bears all physical risk while organizers remain anonymous; Mark got 5 years while sellers faced no charges.
How the Carding Chain Actually Works
Carding—buying and using stolen banking data—remains one of cybercrime's most durable schemes. The process Mark followed is textbook:
- Data Collection: Criminals harvest magnetic stripe data (track 1 and track 2) using credit card skimming device detector-evading hardware on ATMs, shimmer devices inserted into card slots, phishing campaigns, or by purchasing dumps on darknet markets.
- Encoding: Stolen data gets written onto blank plastic cards. The card receives embossed details—cardholder name, expiration date, card number—to mimic legitimate cards.
- PIN Acquisition: If the PIN was captured (via overlay keypads or hidden cameras on ATMs), you receive a complete cash-out tool.
- Withdrawal: You extract cash from ATMs before victims notice unauthorized transactions and request blocks.
- Laundering: Cash converts into cryptocurrency through Bitcoin ATMs or peer-to-peer exchanges, obscuring the money trail.
Mark bought his cards on a marketplace we won't name here. He paid in Monero, chosen specifically because tracking it presents challenges. The cards arrived in plain packaging by mail. Everything appeared successful. But this scheme contains one detail buyers consistently underestimate: an ATM isn't merely a cash machine. It's an evidence-gathering station.
The Surveillance System Mark Ignored
What exactly does a modern ATM record? You might think it's just transaction data. You'd be wrong.
Every contemporary ATM functions as a comprehensive surveillance hub. Inside nearly every machine, you'll find:
- Built-in camera: Aimed directly at your face, recording at 1080p resolution, often equipped with infrared for night recording.
- Secondary hidden camera: Many models install a second camera at a different angle, invisible from outside.
- Transaction log: Every withdrawal gets timestamped to the second—time, amount, card number, ATM identifier, transaction status.
- Geolocation data: The ATM knows its exact coordinates and transmits them to the bank's central log.
- Network metadata: Processor requests get logged, including all connection metadata.
When Mark approached his fourth ATM in a Tampa Bay suburb, the built-in camera captured his face in full profile. No mask. No glasses. No hat. He withdrew $700, retrieved the card, and walked away. Twenty-three seconds of footage. That was sufficient.
Offenders assume darknet anonymity extends into the physical world. But an ATM isn't a darknet node. It's where digital crime becomes physical—and where anonymity ends.
The 15-Day Investigation Timeline
How did authorities move from unauthorized withdrawals to an arrest in two weeks? Here's the exact sequence:
Day 1 (November 2024): Three victims across Florida, Georgia, and North Carolina notice unauthorized withdrawals. They file complaints with their banks. Banks block the cards and feed data into the early fraud warning system.
Day 3: The bank's anti-fraud algorithms detect a pattern—withdrawals from the same batch of cloned cards across multiple states within hours. An automatic flag triggers. The case moves to the bank's investigation unit.
Day 5: The bank transfers the case to the U.S. Secret Service, which handles financial crimes. A USSS analyst requests logs from all involved ATMs plus video recordings.
Day 8: Video from the fourth ATM provides a clear facial image. Comparison against Florida Department of Public Safety driver's license databases returns a match: Mark T., no criminal history. Transaction analysis shows all withdrawals occurred within a 40-mile radius of his registered address.
Day 12: Investigators secure a warrant for electronic traces—browser history, ISP records, cryptocurrency wallet activity. ISP analysis reveals visits to Tor exit nodes during hours matching the purchase timeframe. The Monero wallet links to a darknet marketplace account through a court order to the exchange where Mark bought Monero.
Day 14: A court issues a search warrant for his residence. During the apartment search, authorities seize six blank plastic cards, a magnetic stripe reader/writer (MSR device), a laptop with darknet marketplace visit history and Tor Browser traces, $3,200 in cash, and shipping packaging.
Day 15: Mark is arrested. During interrogation, he admits to purchasing the cards and cashing out four of six. The remaining two failed—banks had already blocked them before his withdrawal attempts.
The Numbers That Tell the Story
Let me show you the financial and legal arithmetic of this case:
| Metric | Value |
|---|---|
| Total ATM withdrawals | 4 |
| Amount withdrawn | $4,900 |
| Cost of cloned cards | $480 |
| Days from first withdrawal to arrest | 15 |
| Federal prison sentence | 5 years (60 months) |
| Fine and restitution combined | $22,000 |
| Supervised release period | 3 years |
The profit-to-punishment ratio tells you everything about card skimming protection systems. Mark gained $4,420 net (before arrest). He'll pay $22,000 and lose five years of freedom. That's not counting the supervised release restrictions afterward.
Why Cryptocurrency Didn't Provide Protection
Mark chose Monero for payment—a cryptocurrency engineered specifically for anonymity. Yet investigators still traced the chain back to him. Where did the credit card skimmer protection system find the weak link?
The Purchase Entry Point
To acquire Monero, Mark used a centralized exchange requiring KYC verification—he uploaded his passport and a selfie. Under court order, the exchange provided his identity and complete transaction history. Although subsequent Monero movement is difficult to track, the purchase fact on the correct date and amount became evidence.
The Time Correlation
Monero purchase, marketplace transaction, card receipt, ATM withdrawals—everything happened within two weeks. This time window coincidence became circumstantial but substantial evidence.
Physical Evidence Trumps Digital Anonymity
The cards found during the search contained magnetic tracks matching dumps stolen from actual victims. This constitutes direct physical evidence that no cryptocurrency can erase. Even if Mark had perfected every digital step, the video alone would have connected him to the crime scene.
How to tell if a card reader has a skimmer becomes irrelevant when you're the one using the skimmed data. The same surveillance tools designed for credit card skimmer protector purposes work equally well identifying criminals using cloned cards.
Mark's Six Critical Mistakes
What exactly went wrong? Let me walk you through each error:
1. Geographic clustering: All four ATMs sat within 40 miles of his home address. Anti-fraud systems immediately flag such patterns as suspicious activity.
2. Zero disguise: No mask, no glasses, no hat. A clear face on camera creates a direct identification path through DPS databases. This is how to check for credit card skimmers in reverse—the same cameras watching for tampering also record faces.
3. Centralized exchange for Monero: KYC requirements linked his real identity to the cryptocurrency purchase he later used for marketplace payment.
4. Evidence storage at home: Cards, MSR device, laptop with browsing history—all recovered during the search. Digital evidence often survives deletion attempts. Tor Browser leaves traces, and operating system logs can indicate usage patterns.
5. Matching cash denominations: The $3,200 seized matched bill denominations dispensed by the ATM. A small detail, but it strengthened prosecution evidence.
6. Compressed timeline: All withdrawals within two weeks. Spreading them over months might have delayed anti-fraud triggers—but cameras would have identified him regardless.
What Security Professionals Can Learn
Mark's case isn't about criminal genius. It demonstrates how security systems function—and function better than most cloned card buyers realize. For cybersecurity professionals, several lessons emerge:
Anti-Fraud Systems as First Defense
Bank-side anti-fraud systems represent the first and often underestimated defense line. Pattern analysis, geolocation rules, scoring models—all operated automatically before human involvement. Banks should continue investing in machine learning models for anomaly detection. This is card skimming protection at scale.
Physical and Digital Forensics Integration
The critical evidence—ATM video—is a physical medium. But without the digital transaction log, the video becomes useless. You need to know exactly when to extract a frame. Integrating these two domains forms the foundation of successful investigations.
Cryptocurrency Anonymity Limitations
So-called "anonymous" cryptocurrencies don't guarantee anonymity. The entry point (KYC exchange) and exit point (cash) are two chain ends linking digital and physical worlds. As long as KYC exists, complete anonymity remains impossible. Card skimming reddit discussions often miss this critical weakness.
Customer Education Gaps
Victims didn't notice fraud immediately. The faster a victim reports theft, the faster banks block cards—and the less fraudsters withdraw. Educational efforts by banks with customers directly reduce damage. Teaching people how to tell if there is a card skimmer matters, but teaching them to monitor accounts matters more.
The Legal Outcome
In March 2025, Mark T. pleaded guilty to charges of fraud and related activity in connection with access devices (18 U.S.C. § 1029) and money laundering (18 U.S.C. § 1957). The U.S. District Court for the Middle District of Florida sentenced him to 60 months in federal prison followed by three years of supervised release.
The court also ordered a $22,000 fine and full restitution to the three victims. In sentencing remarks, the judge noted that Mark wasn't the scheme organizer—he was the buyer, the final link. But it's the final link that bears physical risk and receives physical punishment.
The organizers higher up the chain more often remain in shadows—and that represents a separate problem law enforcement solves more slowly. When you see atm skimmer images or cf card cloning discussions on forums, remember: the people selling this data rarely face consequences. The people using it almost always do.
Where Digital Crime Meets Physical Consequences
Mark's story illustrates a fundamental truth about modern financial crime: anonymity in the digital realm doesn't extend to physical cash-out points. Every ATM withdrawal creates a convergence point where digital crime meets physical evidence—and that's where most criminals get caught.
The credit card skimming protection systems banks deploy aren't just about detecting skimmers. They're about detecting the entire chain, from data theft to cash withdrawal. The same surveillance tools that serve as a credit card skimmer detector for legitimate customers become evidence-gathering tools when crimes occur.
For those exploring darknet markets out of curiosity or desperation, understand this: the anonymity promised by cryptocurrency and Tor ends the moment you interact with the physical world. An ATM camera, a package delivery, a cash deposit—each creates evidence that no amount of digital obfuscation can erase. The card skimming protector systems you try to evade are backed by federal agencies with unlimited patience and resources.
FAQ
How do banks detect cloned card usage so quickly?
Banks use machine learning anti-fraud systems that analyze transaction patterns in real time. Geographic clustering, unusual withdrawal amounts, and rapid successive transactions across multiple states trigger automatic alerts within hours. In Mark's case, the system flagged suspicious activity within three days.
Can Monero or other privacy coins actually protect your identity?
Privacy cryptocurrencies hide transaction trails but not entry and exit points. If you purchase Monero through a KYC exchange (requiring ID verification), authorities can trace you through the purchase record. Mark's anonymity failed because investigators obtained his identity from the exchange where he bought Monero, not from tracking the Monero itself.
What ATM evidence do investigators actually use in court?
Investigators combine video footage (face recordings at 1080p), transaction logs (timestamp, amount, card number, ATM location), and network metadata. This creates a complete evidence package linking a specific person to a specific withdrawal at a specific time and place. Mark's case used all three types.
Why do cloned card buyers get caught while sellers stay anonymous?
Sellers operate entirely in the digital realm and often across international borders, making prosecution difficult. Buyers must physically interact with ATMs to extract cash, creating video evidence and geographic patterns. The physical cash-out point is where digital anonymity ends and where law enforcement focuses resources.
Handpicked links. A few related services may help with the next step. Tools & services